Buying off-plan in Sweden? A price drop can add SEK 270,000 upfront
If the flat's value falls from SEK 3.2 million to SEK 2.9 million before moving day, your down payment grows from SEK 320,000 to SEK 590,000.
If the flat's value falls from SEK 3.2 million to SEK 2.9 million before moving day, your down payment grows from SEK 320,000 to SEK 590,000.
A refusal voids the sale and you get your deposit back. Within 1 month you can go to the rent tribunal. A bylaw demanding a set income has no effect.
An association that borrows SEK 15 million at 3.5% pays SEK 525,000 a year in interest. Find the plans in the annual report, maintenance plan and minutes.
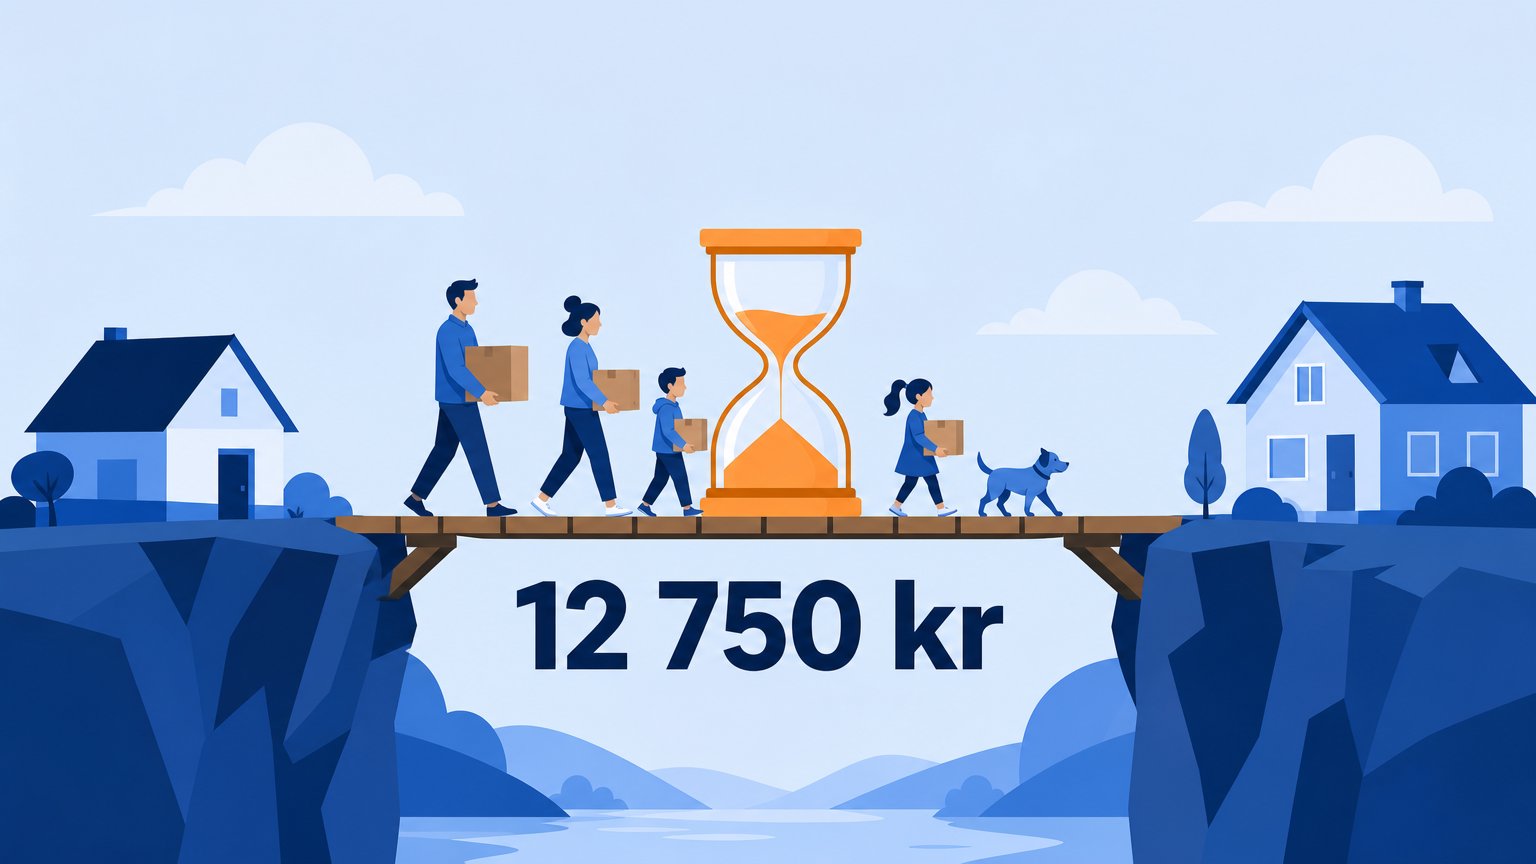
Borrow SEK 1,200,000 at 4.25% and three months of interest cost SEK 12,750. If the loan is unsecured, there is no tax relief from 2026: SEK 3,825 lost.
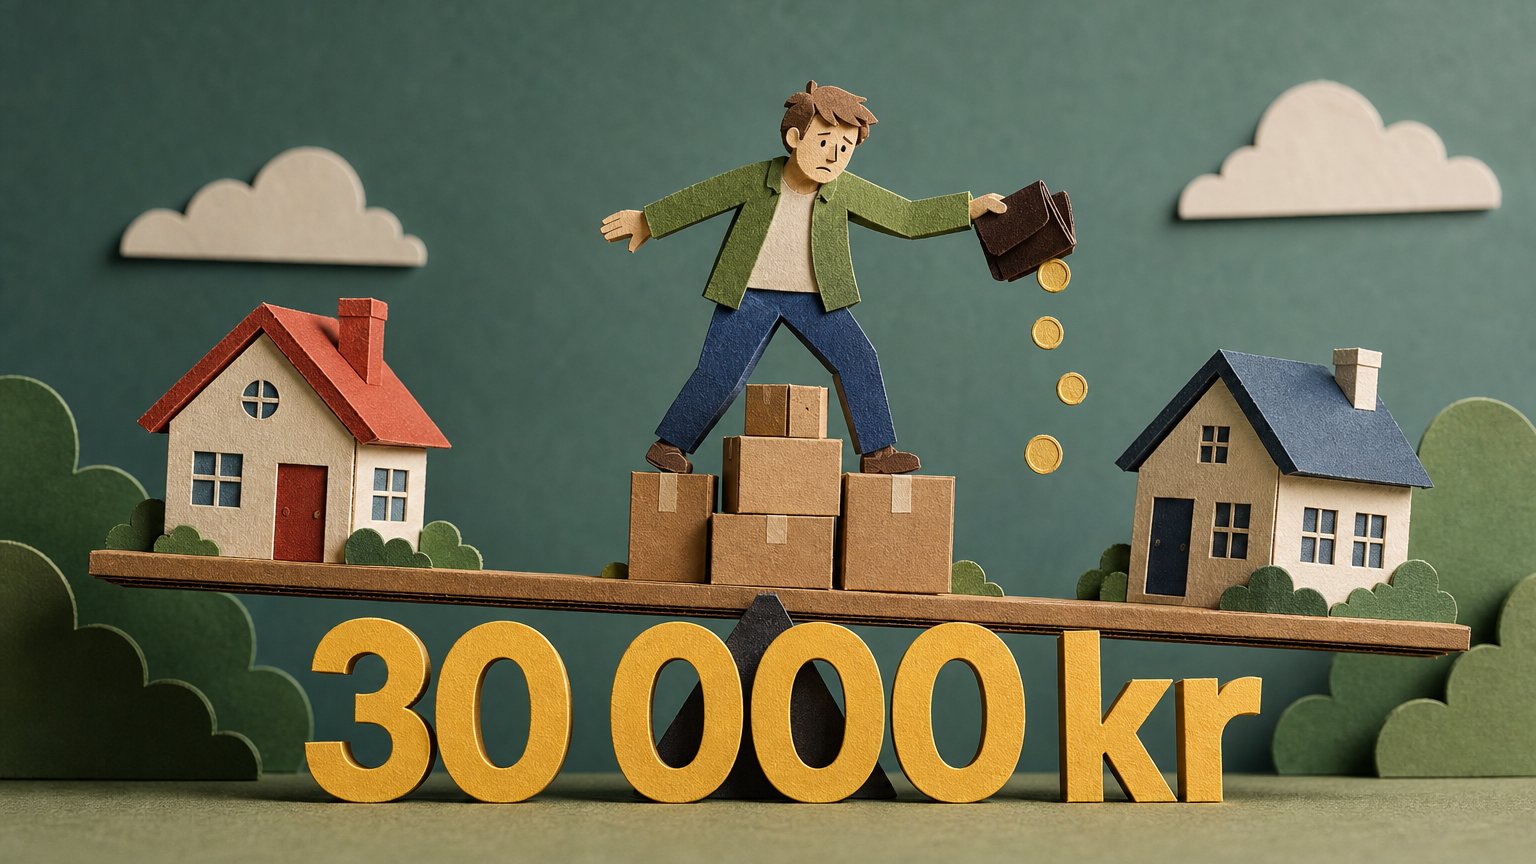
Two months at SEK 15,000 per home adds SEK 30,000. SEB almost always advises selling first, and SBAB suggests completion three to six months out.
Folksam's flood excess is 10% of the damage, at least SEK 10,000. Water that seeps in through the foundation is usually not covered at all.
With a SEK 4,000,000 house and a SEK 2,000,000 loan you can borrow SEK 1,200,000 more. At 80%, amortization comes to SEK 5,333 a month.
Pay SEK 300,000 of a SEK 400,000 down payment and you still get only half. A written cohabitation agreement plus a promissory note changes the split.
Your bank pays SEK 2,880,000, the seller's loans are cleared and you sign the deed of sale. Then you have three months to apply for title registration.
Stamp duty is 1.5% of the price plus SEK 825. New deeds for SEK 1.4m add SEK 28,375, so you pay SEK 89,200 on top of the down payment.
A signed purchase contract has no cooling-off period. On a SEK 3.5 million house the seller can keep SEK 350,000 and claim more if the loss is larger.
If the bank says no after you sign, you are still bound, and a SEK 350,000 deposit can be lost. A written loan condition lets you reverse the sale.
You can claim a hidden defect from the seller for up to 10 years. In a 1998 Supreme Court case, mould the inspection had warned of did not count.
A SEK 2.5 million flat needs SEK 250,000 down, but costs just under SEK 500 more a month. The bank's stress rate decides how much you can borrow.
The cap is 90% and the stricter amortization rule is gone. On existing loans you must ask your bank yourself, and top-up loans stop at 80%.
Interest sensitivity of 17% means your fee can rise from SEK 4,500 to SEK 5,250 a month if the association's rate goes up 1 point.
A SEK 3.2 million bid binds neither you nor the seller until the contract is signed. The seller can pick a lower bid, and you can walk away.
A SEK 2.8 million two-room flat can cost SEK 12,046 a month. Check recent sale prices, the association's loans and the bathroom before your first bid.
With a 90% cap, SEK 300,000 is enough for a SEK 3 million home, but the monthly cost rises about SEK 480. Parliament has yet to vote on the proposal.
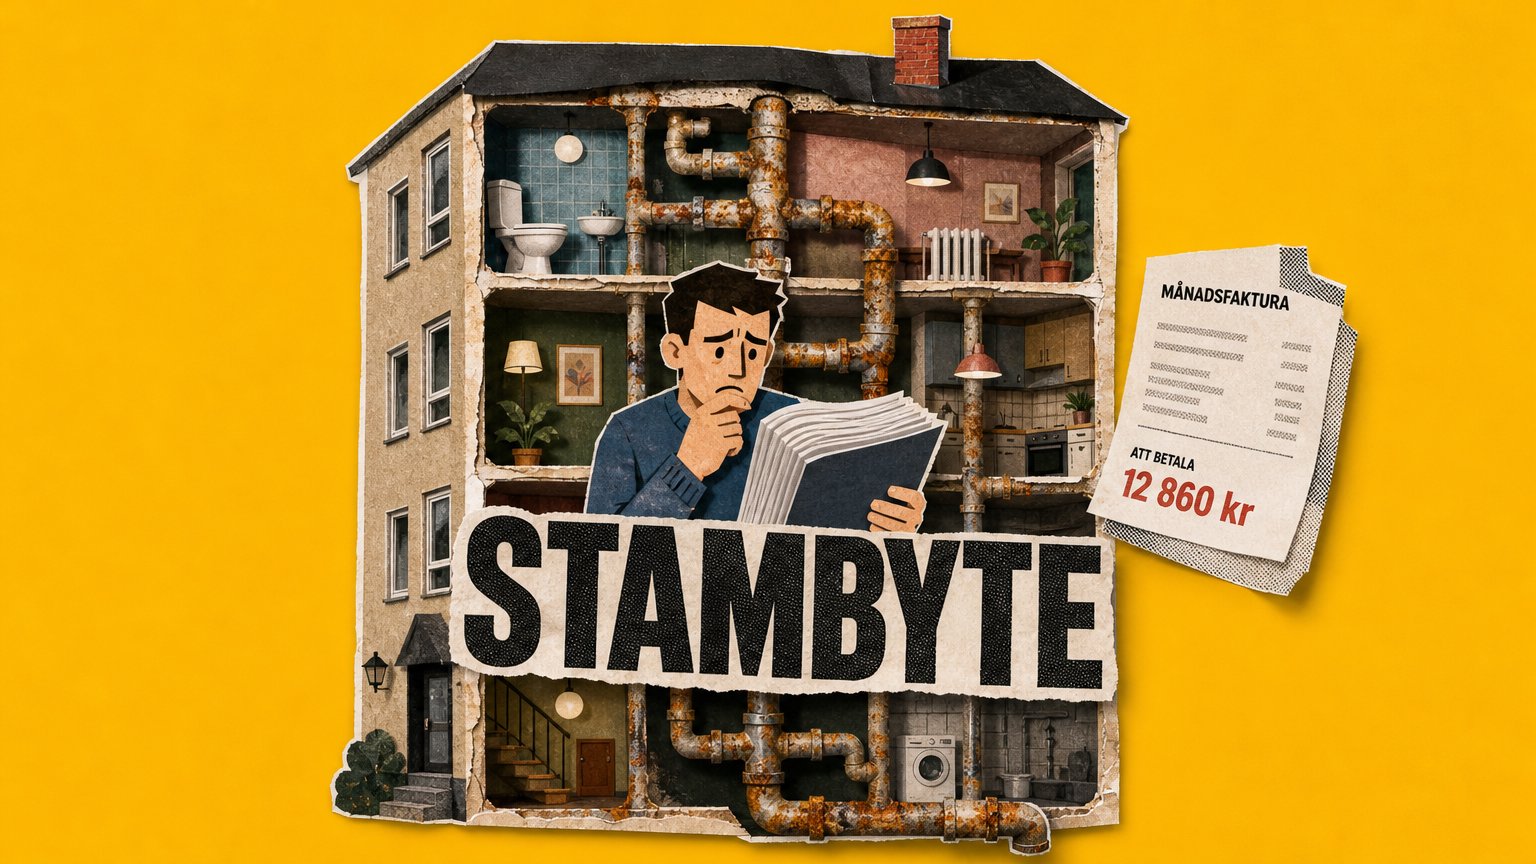
In a house you pay for the whole roof. In a co-op the association pays, but through the fee: a SEK 10 million pipe job can add SEK 833 a month.
Each bank sets how long a pre-approval lasts, 6 months at Swedbank. It does not bind the bank, so apply at one or two banks, not five.
The cap would rise to 90% and the stricter amortization rule would go. On a SEK 3 million home, the down payment drops from SEK 450,000 to SEK 300,000.
Banks test at a 7% rate. A couple on SEK 70,000 a month keep SEK 24,665, but only SEK 15,790 if the loan grows to SEK 4.25 million.
A SEK 150,000 personal loan at 8% costs SEK 12,000 a year, with no tax relief from 1 January 2026. Banks also count it when they test your mortgage.
A SEK 4 million house costs SEK 16,923 a month and a SEK 3 million co-op flat SEK 12,892, counting interest, amortization, running costs and fee.