Swedish one-year mortgages: median up to 3.10% in September 2026
The banks' one-year median was 2.84% in September 2025. A year later it stood at 3.10%. JAK Medlemsbank was lowest at 2.60%.
Short news about mortgage rates, the Riksbank and the housing market.
The banks' one-year median was 2.84% in September 2025. A year later it stood at 3.10%. JAK Medlemsbank was lowest at 2.60%.
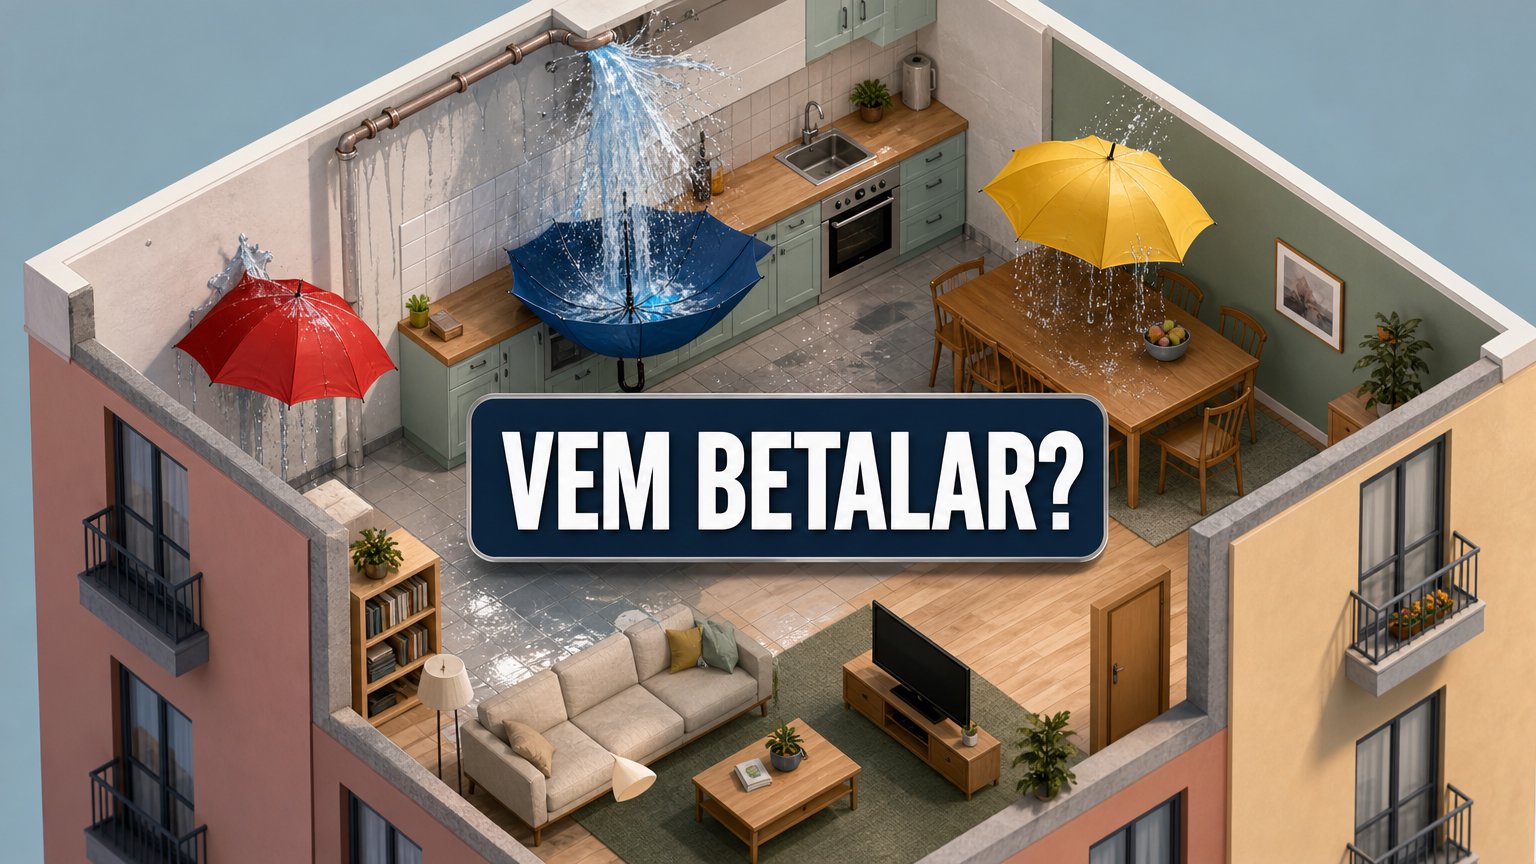
If the association's main pipe leaks, it pays for the SEK 60,000 floor. Your home insurance pays for the SEK 15,000 sofa, minus the excess.
CPIF inflation rose from 0.7% in August 2026. Electricity rose 11.7% and fuel 13.3% in one month. The Riksbank's next rate decision is on 4 November 2026.
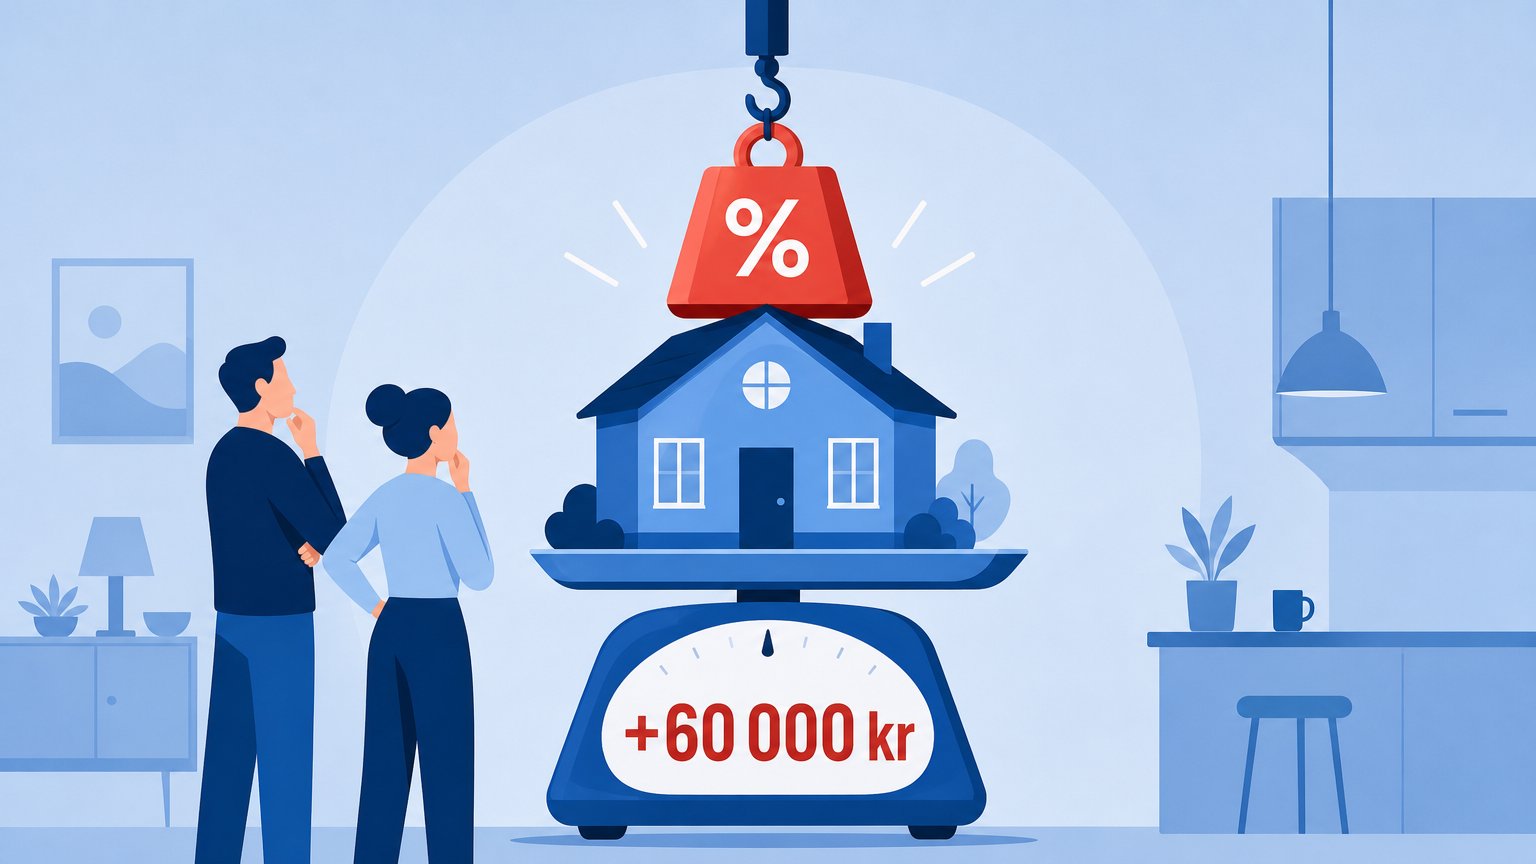
On a SEK 3,000,000 loan that is SEK 60,000 more a year before tax relief. Borrow alone and the rise costs about SEK 45,700 after relief, not SEK 42,000.
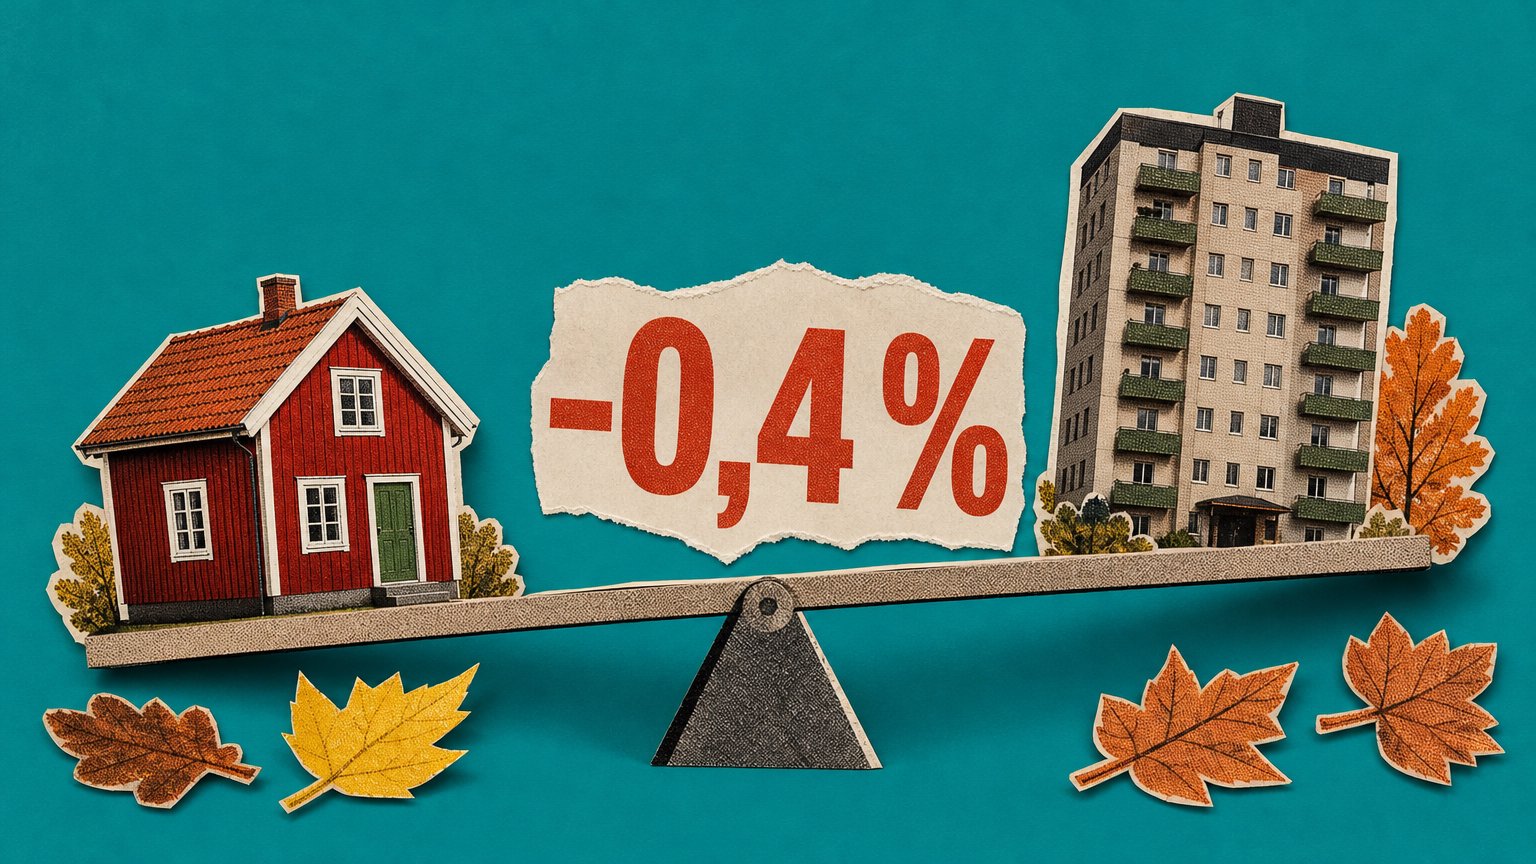
On a SEK 4,000,000 house the drop equals about SEK 16,000. It is the first fall for houses since January 2026, says Svensk Mäklarstatistik.
SEB's August 2026 averages: 2.67% variable, 3.16% fixed for three years. On the Riksbank forecast, fixing saves only about SEK 1,800 a year.
Banks fund fixed mortgages with bonds. The yield on two-year mortgage bonds rose from 2.42% on 1 July 2026 to 3.13% on 18 September 2026.
Hikes should start in 2026. If banks follow, a variable SEK 3,000,000 loan may cost about SEK 19,000 more a year, SEK 13,000 after tax relief.
If the flat's value falls from SEK 3.2 million to SEK 2.9 million before moving day, your down payment grows from SEK 320,000 to SEK 590,000.
The rise is 0.25 points and can add SEK 7,500 a year to a SEK 3,000,000 loan. Variable rates stay put. Five other banks raised fixed rates first.
A refusal voids the sale and you get your deposit back. Within 1 month you can go to the rent tribunal. A bylaw demanding a set income has no effect.
Skurups Sparbank had the lowest three-year average in August 2026 at 3.03%, down from 3.05%. Skandia stayed lowest on variable rates at 2.58%.