Sweden's policy rate is flat at 1.75%: why fixed mortgages cost more
Banks fund fixed mortgages with bonds. The yield on two-year mortgage bonds rose from 2.42% on 1 July 2026 to 3.13% on 18 September 2026.
Banks fund fixed mortgages with bonds. The yield on two-year mortgage bonds rose from 2.42% on 1 July 2026 to 3.13% on 18 September 2026.
Hikes should start in 2026. If banks follow, a variable SEK 3,000,000 loan may cost about SEK 19,000 more a year, SEK 13,000 after tax relief.
The rise is 0.25 points and can add SEK 7,500 a year to a SEK 3,000,000 loan. Variable rates stay put. Five other banks raised fixed rates first.
The gap between the highest and lowest average rate was 0.19 points, or SEK 5,700 a year on SEK 3m. Who owns the lender decides whether you must negotiate.
Card packages and dearer funds can eat the gain. In the example with a SEK 3,000,000 mortgage, only SEK 560 a year is left once the fees are paid.
Below 70%, 1% amortization is enough, and SBAB's example rates apply at 60% or less. Your lender must show how it worked out your loan-to-value.
Sörmlands Sparbank's three-year average fell from 3.51% to 3.14% in May 2026. Only Swedbank's 3.09% was lower. Danske Bank was second on variable at 2.67%.
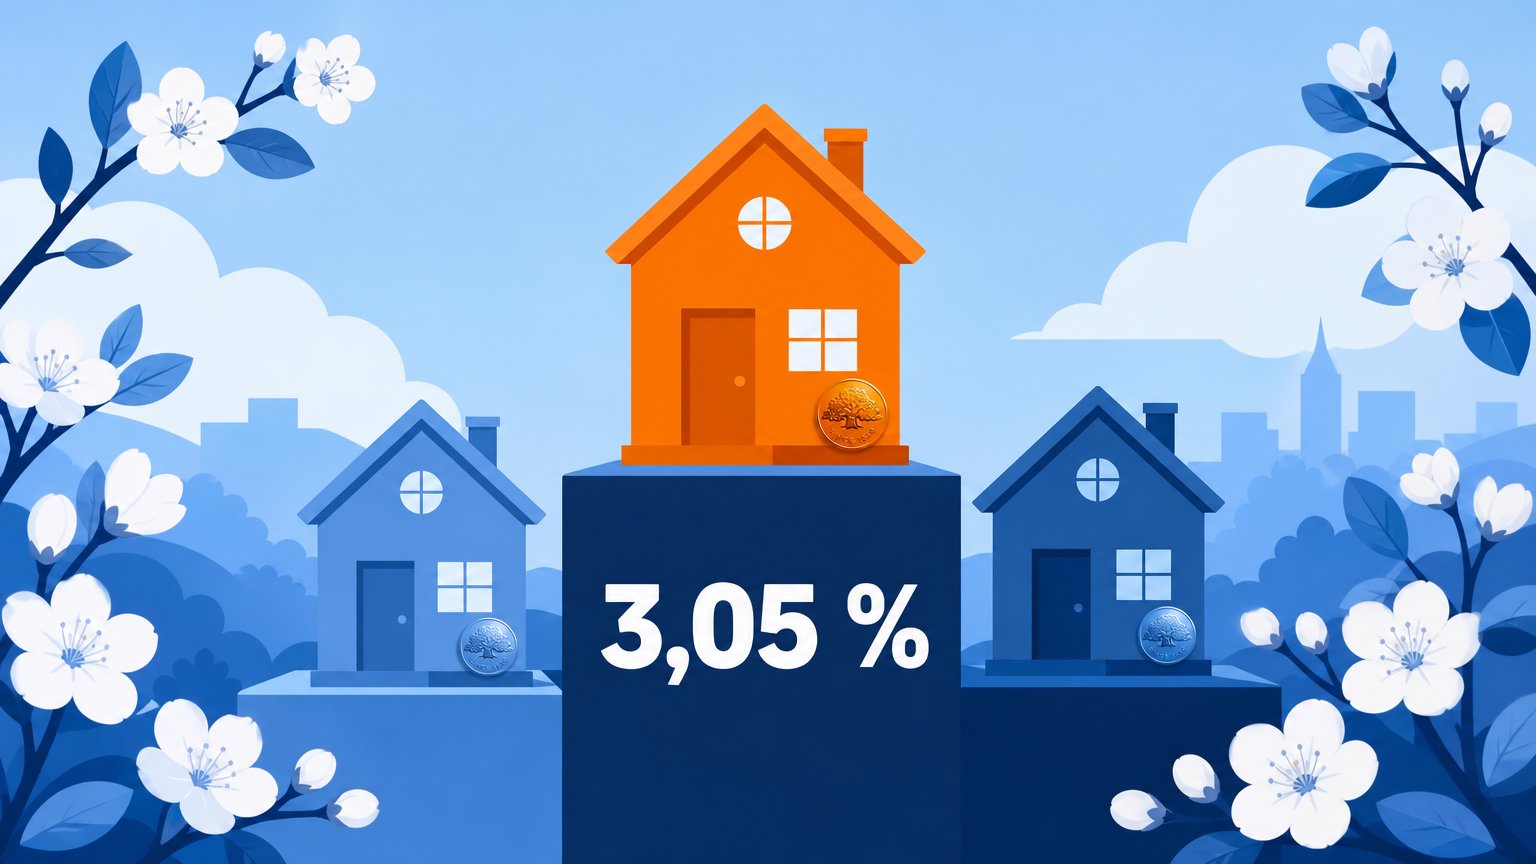
At 3.05%, Swedbank passed Sparbanken Mälardalen on three-year fixes in April 2026. The banks' median rose for every rate period from March 2026.
The cap is 90% and the stricter amortization rule is gone. On existing loans you must ask your bank yourself, and top-up loans stop at 80%.
Swedbank, Nordea and Danske Bank lift variable list rates to 3.89-3.99%. On a SEK 3 million loan that is SEK 4,500 a year, SEK 3,150 after tax relief.
Ålandsbanken's average variable rate of 2.55% beat Skandia's 2.56% in January 2026. The banks' median rose for every rate period from December 2025.
Each bank sets how long a pre-approval lasts, 6 months at Swedbank. It does not bind the bank, so apply at one or two banks, not five.
On a SEK 3 million mortgage, 0.2 points off saves SEK 6,000 a year, or SEK 4,200 after tax relief. Your bank's own average rate is your best argument.