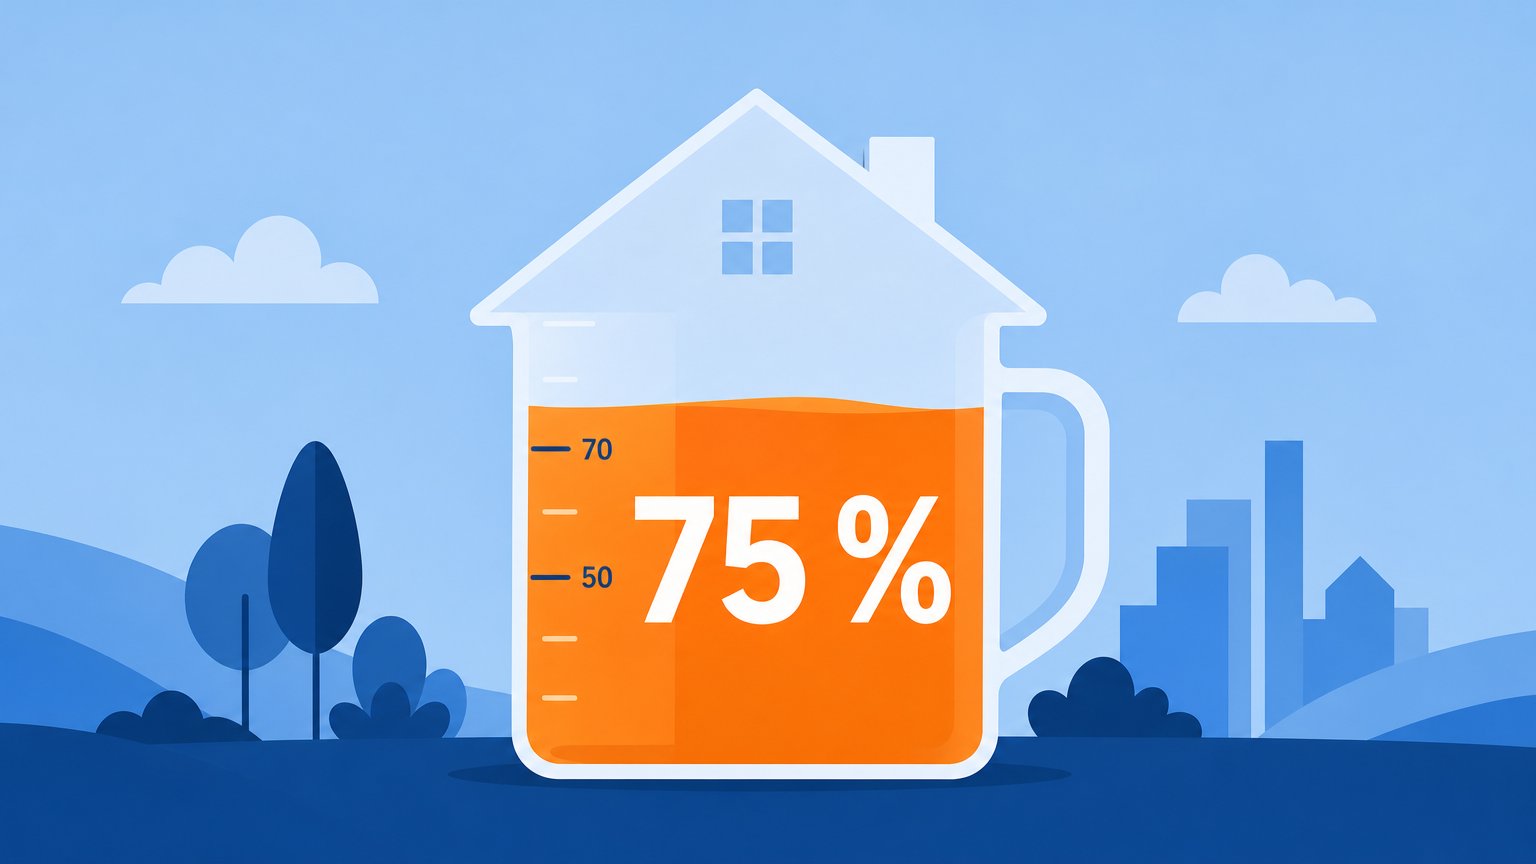
75% loan-to-value in Sweden: SEK 60,000 a year to amortize on SEK 3m
Below 70%, 1% amortization is enough, and SBAB's example rates apply at 60% or less. Your lender must show how it worked out your loan-to-value.
Below 70%, 1% amortization is enough, and SBAB's example rates apply at 60% or less. Your lender must show how it worked out your loan-to-value.
With a SEK 4,000,000 house and a SEK 2,000,000 loan you can borrow SEK 1,200,000 more. At 80%, amortization comes to SEK 5,333 a month.
With SEK 3,400,000 borrowed on a SEK 4,000,000 house you are at 85%. At 2% amortization it takes just under 3 years before the bank can lend more.
With a 90% loan, a SEK 1,500,000 cottage costs about SEK 5,400 a month in interest and amortization at 2.8%. A top-up on your house stops at 80%.
A SEK 2.5 million flat needs SEK 250,000 down, but costs just under SEK 500 more a month. The bank's stress rate decides how much you can borrow.
The stricter amortization rule ended on 1 April 2026, but existing loans change only if your bank agrees. On SEK 3 million: SEK 2,500 less a month.
The cap is 90% and the stricter amortization rule is gone. On existing loans you must ask your bank yourself, and top-up loans stop at 80%.
With a 90% cap, SEK 300,000 is enough for a SEK 3 million home, but the monthly cost rises about SEK 480. Parliament has yet to vote on the proposal.
A SEK 3.4 million loan and a SEK 600,000 household income mean SEK 102,000 a year in amortization. Without the income rule it would be SEK 68,000.
The cap would rise to 90% and the stricter amortization rule would go. On a SEK 3 million home, the down payment drops from SEK 450,000 to SEK 300,000.
Banks test at a 7% rate. A couple on SEK 70,000 a month keep SEK 24,665, but only SEK 15,790 if the loan grows to SEK 4.25 million.
A SEK 150,000 personal loan at 8% costs SEK 12,000 a year, with no tax relief from 1 January 2026. Banks also count it when they test your mortgage.