Swedish one-year mortgages: median up to 3.10% in September 2026
The banks' one-year median was 2.84% in September 2025. A year later it stood at 3.10%. JAK Medlemsbank was lowest at 2.60%.
The banks' one-year median was 2.84% in September 2025. A year later it stood at 3.10%. JAK Medlemsbank was lowest at 2.60%.
Banks fund fixed mortgages with bonds. The yield on two-year mortgage bonds rose from 2.42% on 1 July 2026 to 3.13% on 18 September 2026.
The rise is 0.25 points and can add SEK 7,500 a year to a SEK 3,000,000 loan. Variable rates stay put. Five other banks raised fixed rates first.
Borrow SEK 1,200,000 at 4.25% and three months of interest cost SEK 12,750. If the loan is unsecured, there is no tax relief from 2026: SEK 3,825 lost.
Two months at SEK 15,000 per home adds SEK 30,000. SEB almost always advises selling first, and SBAB suggests completion three to six months out.
On a SEK 3,000,000 loan the gap is SEK 35,100 a year before tax relief. Compare your rate with your bank's average rate and use the gap to negotiate.
With a SEK 4,000,000 house and a SEK 2,000,000 loan you can borrow SEK 1,200,000 more. At 80%, amortization comes to SEK 5,333 a month.
Pay SEK 300,000 of a SEK 400,000 down payment and you still get only half. A written cohabitation agreement plus a promissory note changes the split.
Your bank pays SEK 2,880,000, the seller's loans are cleared and you sign the deed of sale. Then you have three months to apply for title registration.
With a 90% loan, a SEK 1,500,000 cottage costs about SEK 5,400 a month in interest and amortization at 2.8%. A top-up on your house stops at 80%.
A signed purchase contract has no cooling-off period. On a SEK 3.5 million house the seller can keep SEK 350,000 and claim more if the loss is larger.
If the bank says no after you sign, you are still bound, and a SEK 350,000 deposit can be lost. A written loan condition lets you reverse the sale.
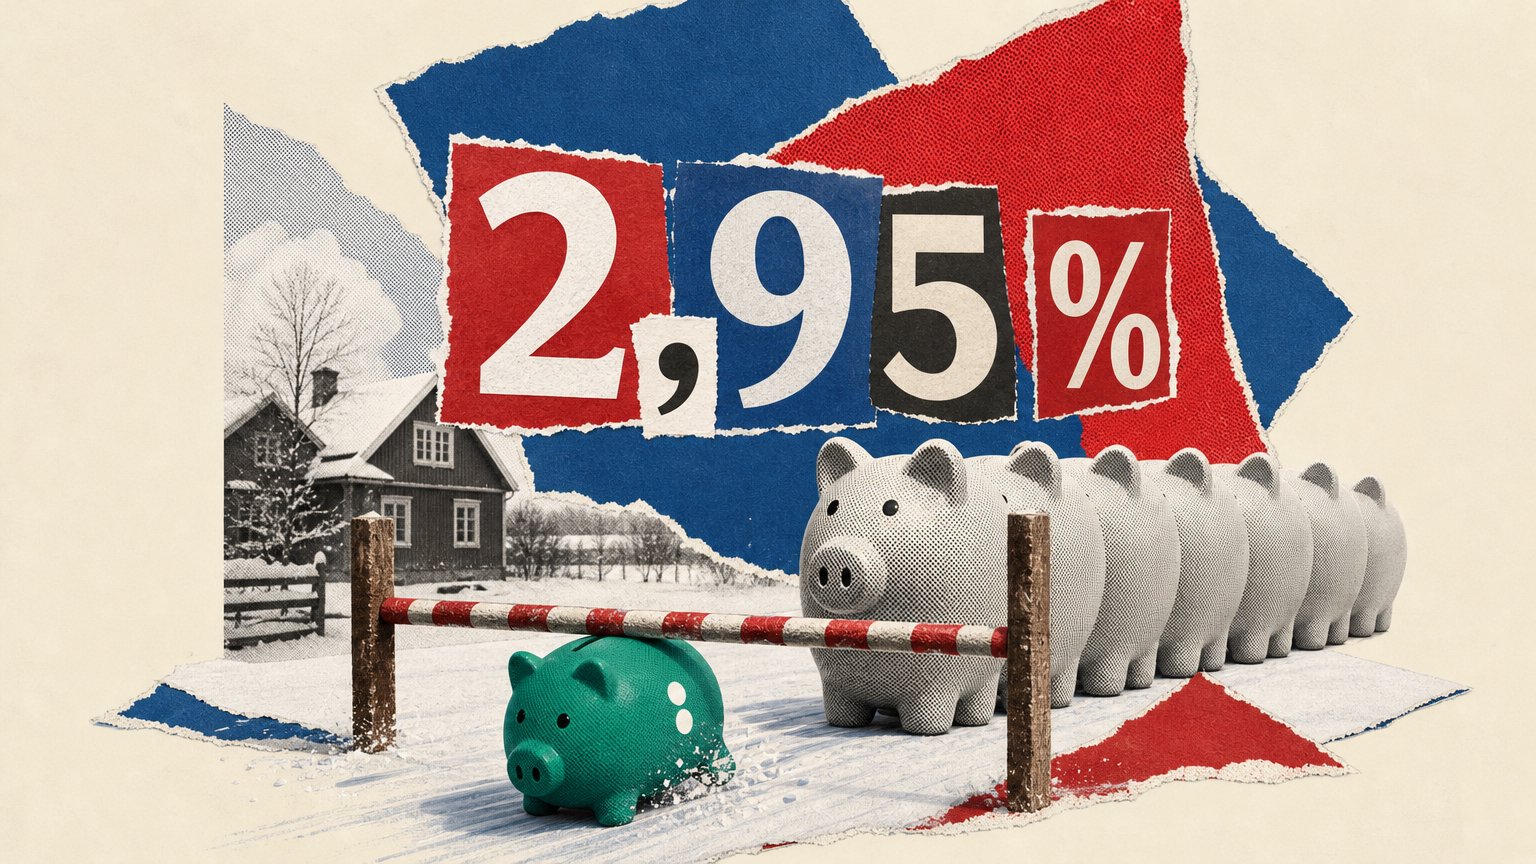
Sparbanken Mälardalen was lowest and ICA Banken highest on three-year fixes in March 2026. Skandia cut 0.11 percentage points to 2.92%, passing Swedbank.
Swedbank, Nordea and Danske Bank lift variable list rates to 3.89-3.99%. On a SEK 3 million loan that is SEK 4,500 a year, SEK 3,150 after tax relief.
Ålandsbanken's average variable rate of 2.55% beat Skandia's 2.56% in January 2026. The banks' median rose for every rate period from December 2025.
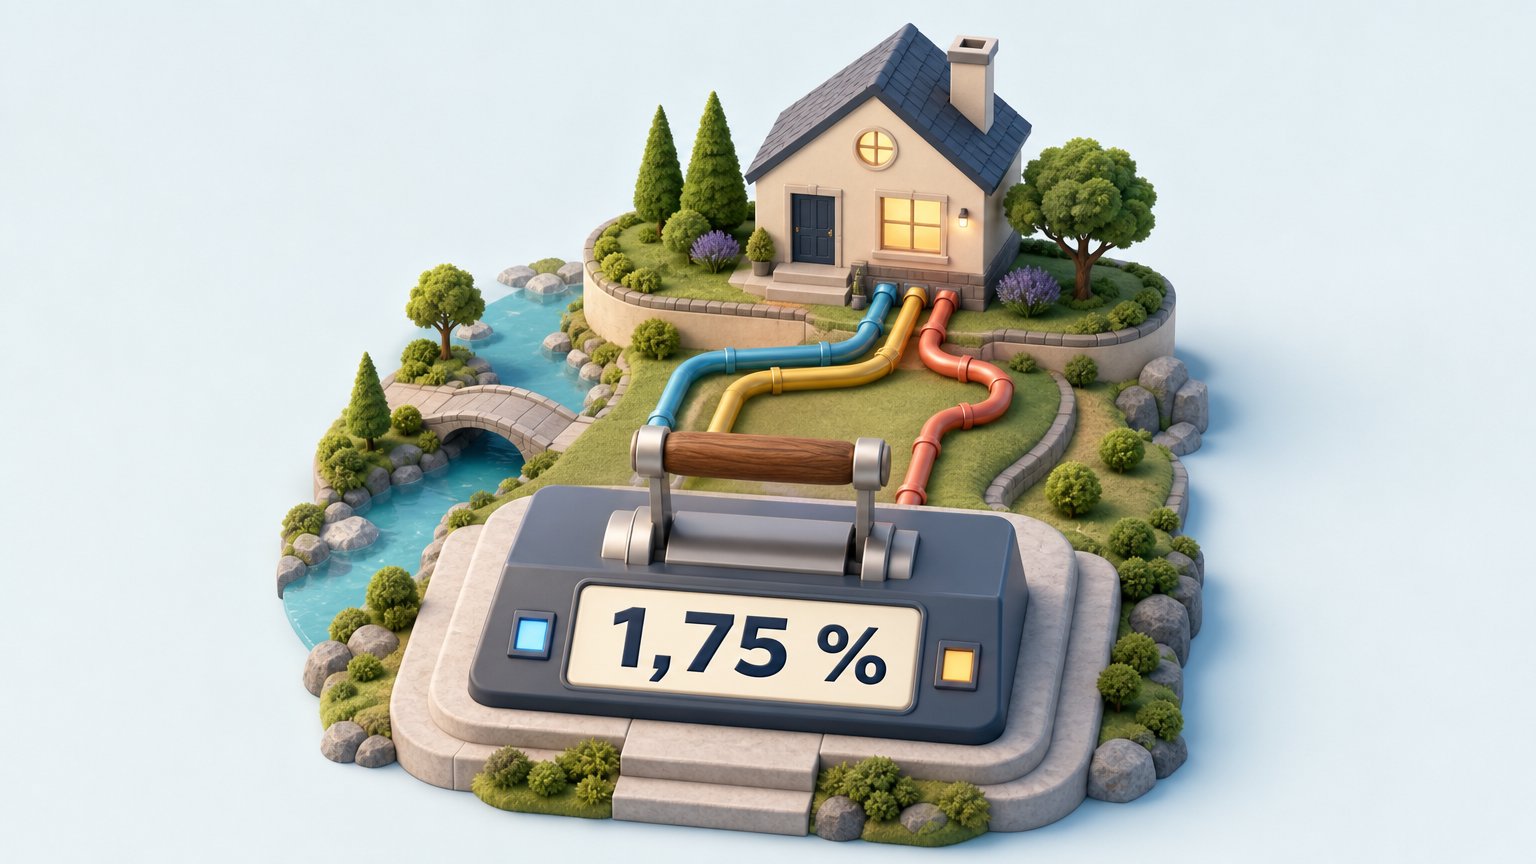
The policy rate is 1.75%. A 0.25-point move changes a SEK 3 million variable loan by SEK 7,500 a year. Fixed rates follow the bond market instead.
JAK Medlemsbank held its one-year average at 2.42% in December 2025. Skandia was lowest on variable at 2.51%, Skurups Sparbank on three years at 2.72%.