Swedish mortgage rate up 2 points? Can you pay SEK 3,500 more a month
On a SEK 3,000,000 loan that is SEK 60,000 more a year before tax relief. Borrow alone and the rise costs about SEK 45,700 after relief, not SEK 42,000.
On a SEK 3,000,000 loan that is SEK 60,000 more a year before tax relief. Borrow alone and the rise costs about SEK 45,700 after relief, not SEK 42,000.
SEB's August 2026 averages: 2.67% variable, 3.16% fixed for three years. On the Riksbank forecast, fixing saves only about SEK 1,800 a year.
Hikes should start in 2026. If banks follow, a variable SEK 3,000,000 loan may cost about SEK 19,000 more a year, SEK 13,000 after tax relief.
Inflation and growth in summer 2026 beat the Riksbank's forecast. A 0.25-point hike would add SEK 7,500 a year to a SEK 3 million mortgage.
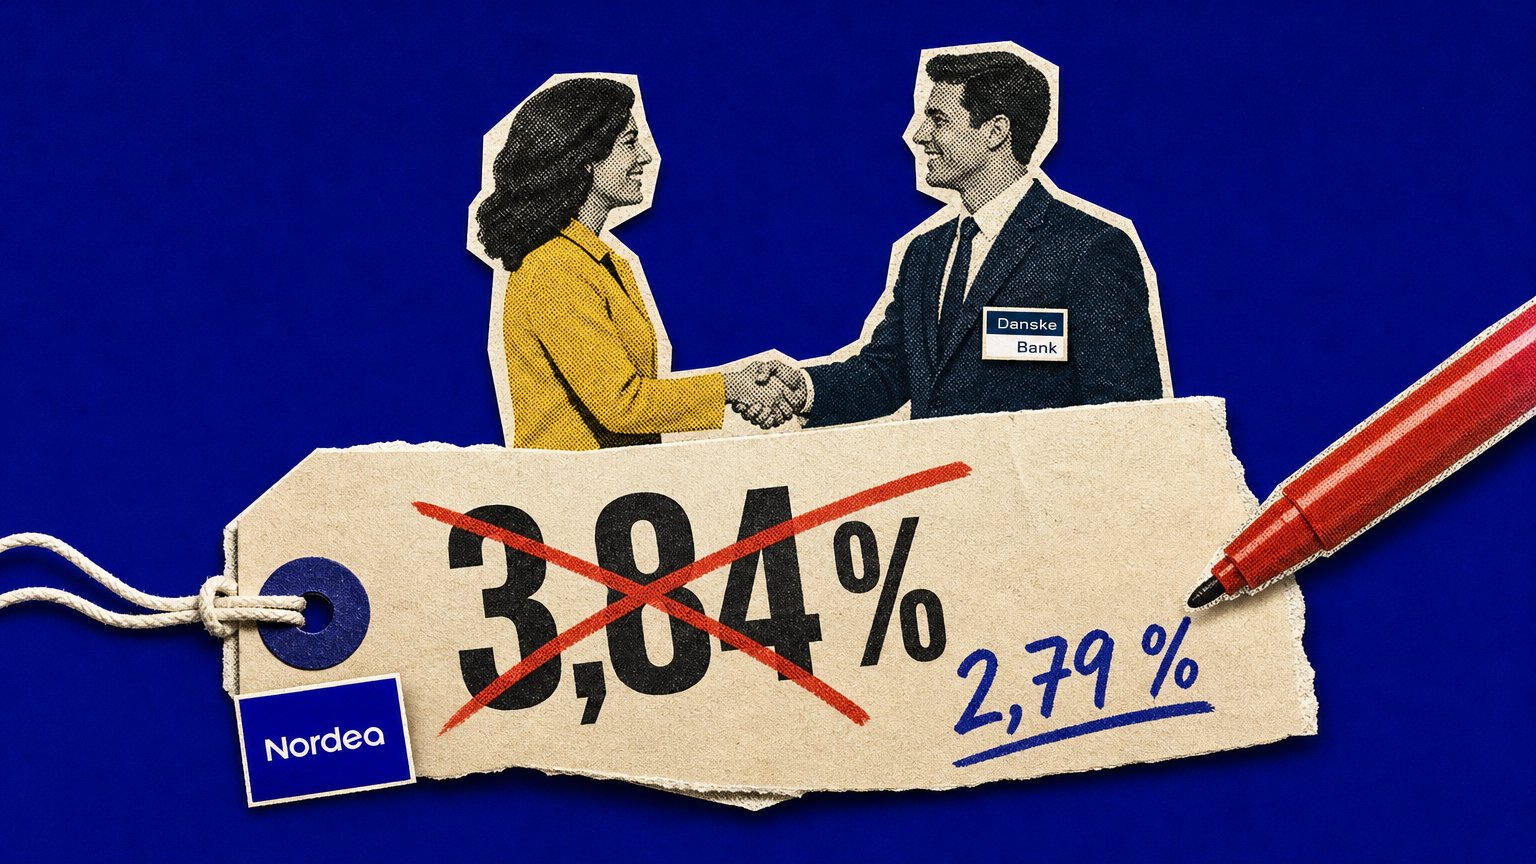
On a SEK 3,000,000 loan the gap is SEK 35,100 a year before tax relief. Compare your rate with your bank's average rate and use the gap to negotiate.
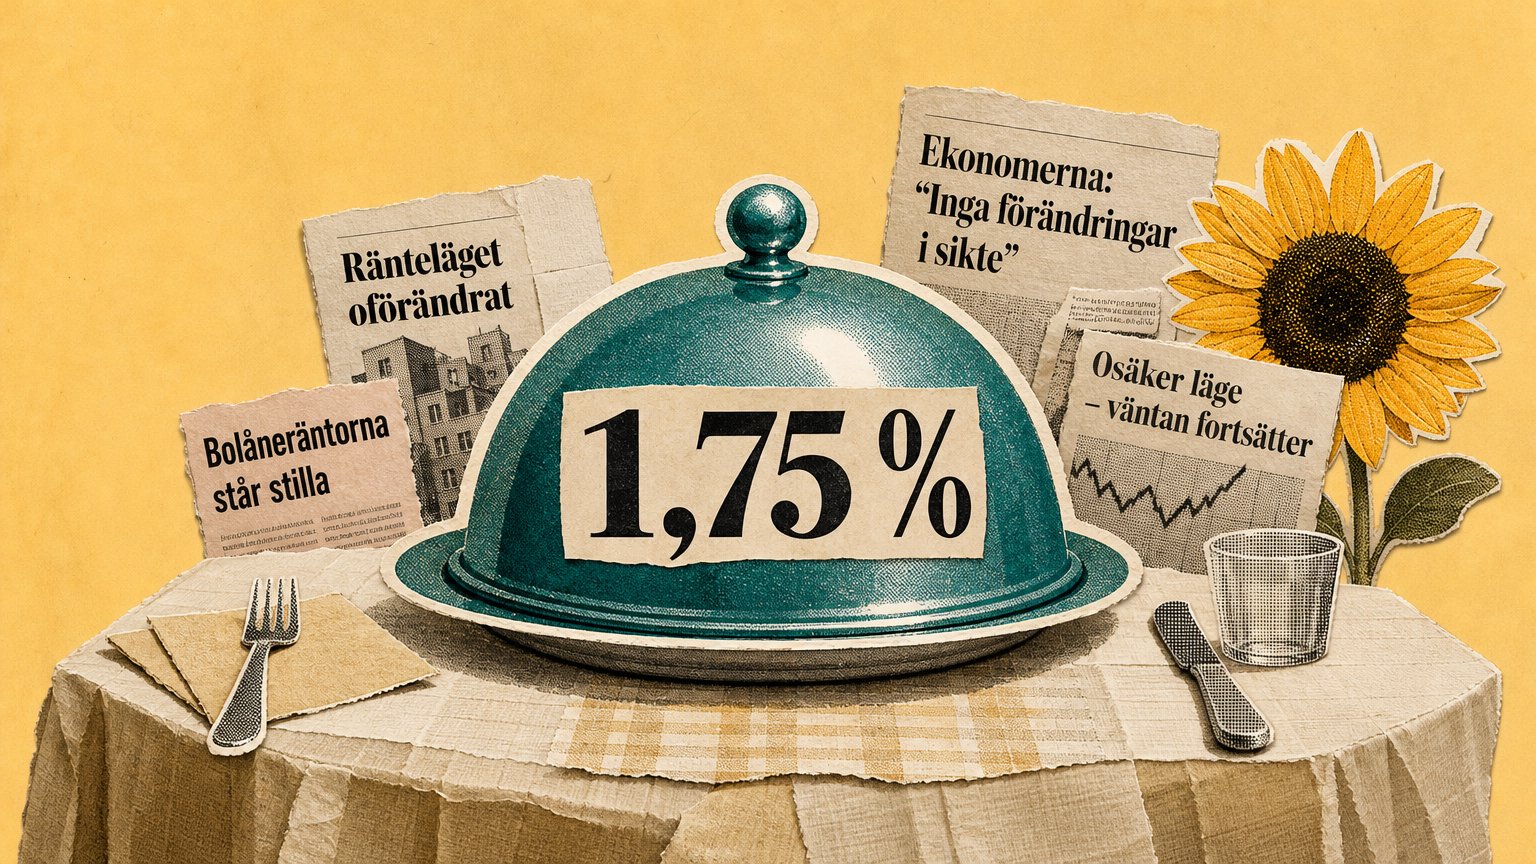
The policy rate stays at 1.75% on 17 June 2026. In our example, a variable rate still beats a two-year fixed rate even after a 0.25-point hike.
CPIF inflation fell to 0.8% in April 2026 and growth is weak. The Riksbank may still raise rates if the Middle East war sets off broad inflation.
Swedbank, Nordea and Danske Bank lift variable list rates to 3.89-3.99%. On a SEK 3 million loan that is SEK 4,500 a year, SEK 3,150 after tax relief.
The CPIF inflation forecast for 2026 rises from 0.9% to 1.5% on energy prices. Short market rates are up, so variable mortgages can still get dearer.
The policy rate stays at 1.75% for some time. A SEK 3 million variable loan costs about SEK 4,585 a month after tax relief. Next decision: 19 March 2026.
The policy rate is 1.75%. A 0.25-point move changes a SEK 3 million variable loan by SEK 7,500 a year. Fixed rates follow the bond market instead.
On a SEK 3 million mortgage, 0.2 points off saves SEK 6,000 a year, or SEK 4,200 after tax relief. Your bank's own average rate is your best argument.